

Trinity Co-operative Credit Union Limited posted total assets amounting to GH¢10.34 million in 2025, marking a 36.2 percent rise compared with the GH¢7.59 million recorded in 2024.
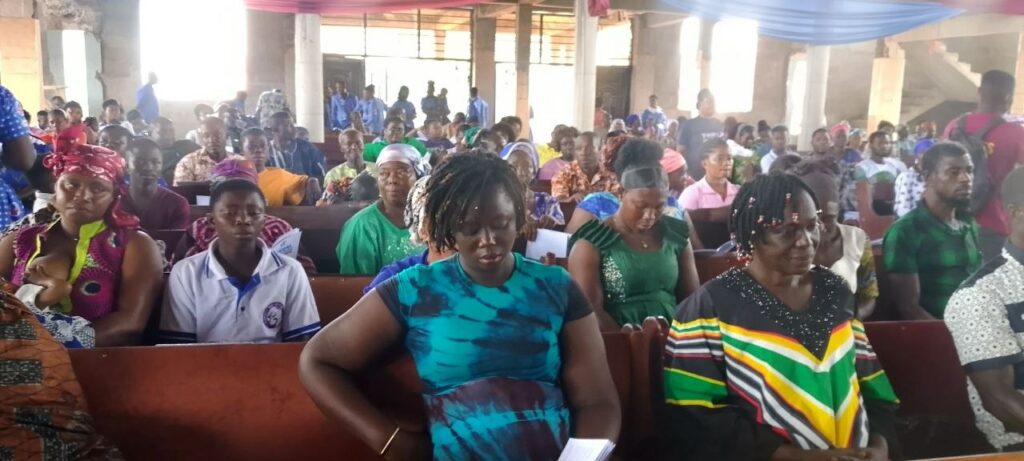
These details appeared in the organisation’s Statement of Financial Position, which was tabled during its Annual General Meeting at the Trinity Presbyterian Church in Techiman on Saturday, 10 October 2026.
Juliana Kobeta, Manager of Trinity Co-operative Credit Union Limited, noted that the body had shown financial strength even after the banking difficulties Ghana faced several years earlier.
She observed that the expansion of the credit union illustrated the trust that residents of Techiman and nearby areas had developed in it as a reliable financial ally.
“When we examine our financial statements and the Co-operative’s progress against the backdrop of the national economic climate, the growth numbers plainly indicate that the people of Techiman and the surrounding districts have embraced Trinity Co-operative Credit Union Limited as their dependable financial partner,” she stated.
Mrs Kobeta urged potential members to enrol with the credit union, stressing that its activities were shaped by the ethical standards and moral foundations of the Presbyterian Church.

“As a financial body operating under the Presbyterian Church, we uphold firm values and principles that direct our professional conduct and promote the collective financial advancement of every member,” she remarked.
Board Chairman Felix Adjei Okang emphasised that ownership of the credit union rested with its members, who stood to gain from the savings and lending facilities it provided.
“Whereas many other financial bodies give the impression of belonging to a select group of shareholders, Trinity Co-operative Credit Union Limited is the property of every member of the Co-operative,” he declared.
Mr Okang clarified that acquiring shares conferred membership of the Union and gave holders the right to dividends at year-end, while savings began to attract interest after a three-month period.
“By purchasing shares you become a member of the Union and are entitled to dividends when the year closes. Moreover, once savings have been held for three months, interest is paid on those funds,” he explained.
He further noted that the credit union made available a range of loan options carrying modest interest charges and offering adaptable repayment terms.

“Additionally, we provide several categories of loans at modest interest rates, accompanied by highly adaptable repayment schedules,” Mr Okang added.
According to the financial statement, members’ savings grew from GH¢7.33 million in 2024 to GH¢9.66 million in 2025, an increase of roughly 31.9 percent.
Net loans extended to members likewise rose from GH¢1.96 million to GH¢4.69 million across the same interval, and members’ shares advanced from GH¢328,802.02 to GH¢398,667.47.

Total equity of the credit union climbed from GH¢256,921.84 in 2024 to GH¢669,620.60 in 2025. Reserves, inclusive of net surplus, also recovered from a deficit of GH¢71,880.18 to a positive balance of GH¢270,953.13.
Overall, the results demonstrate expansion in the institution’s total assets, members’ deposits, loan book and equity throughout the 2025 financial year.
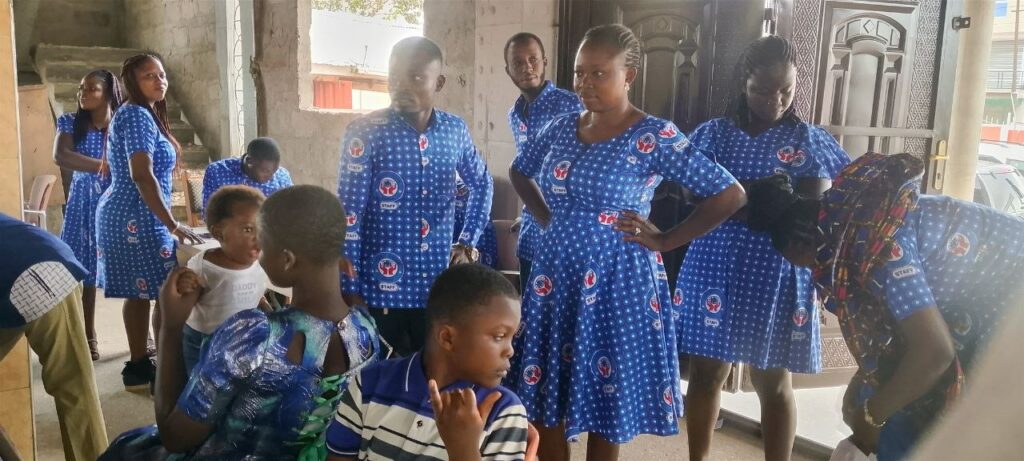
Members present at the meeting expressed their appreciation for the credit union’s consistent service, transparent operations and the tangible support it continues to provide to their households and businesses.
Source: Newspyramid.com
